All Categories
Featured

Best IUL Strategies for Wealth Growth
Table of Contents
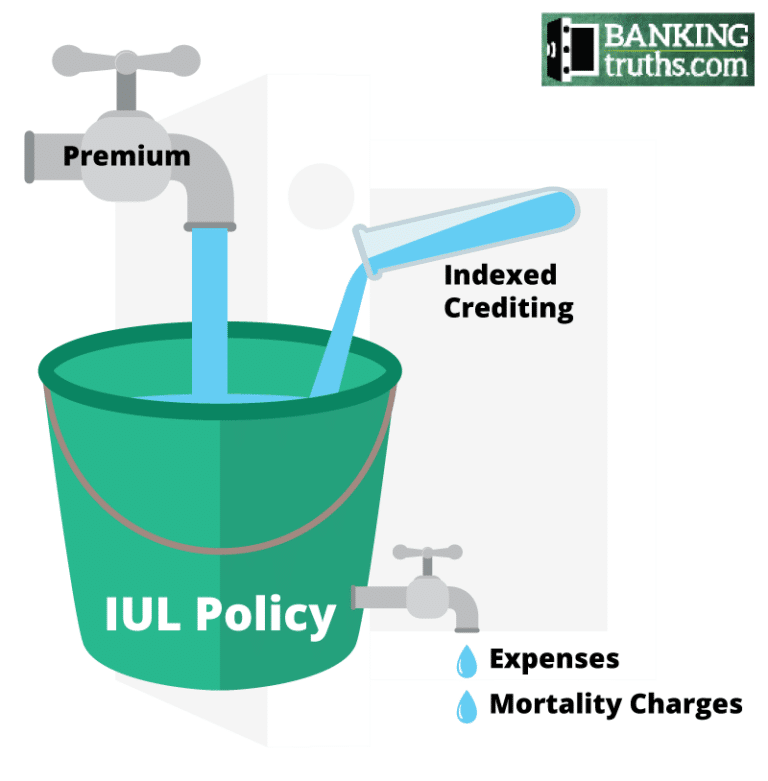
These exact same Indexed Universal Life items will substantially underperform if they're light funded and/or their performance lacks. That suggests that the internal cost load baked into the product is higher than it must be, and heavily reliant on performance to outrun the costs. These poorly developed products that get sold to the unwary masses are the factor you frequently hear IUL is a continuous combo of debits and credits, so it's smart to know what both sides of the ledger appear like.
It's quite standard these days for the majority of IUL policies to have some sort of getting involved loan choice, where your cash worth still has market direct exposure even while obtaining versus it for emergency situations or chances. It's smart to consider the spread in between whatever the loan rate is and the cap so you understand what kind of positive arbitrage you can expect in bullish years.
Having a built-in system to capture this prospective arbitrage will be important in selecting the best-performing IUL policy. There are IUL calculators to assist you determine if you can expect long-lasting favorable arbitrage on your money worth over various timeframes throughout bull and bearish market. Same age, same score, Very same premiumDifferent companies, Various styles, Drastically various money valuesSee how your policy accumulates.
For these factors,, who is remaining abreast of this quickly altering market and can alert you to the latest news and chances. It's not surprising that Penn Mutual ranks the highest of the very best IUL business in regards to warranties because they likewise use the best-performing Whole Life policy, a product understood for its warranties.
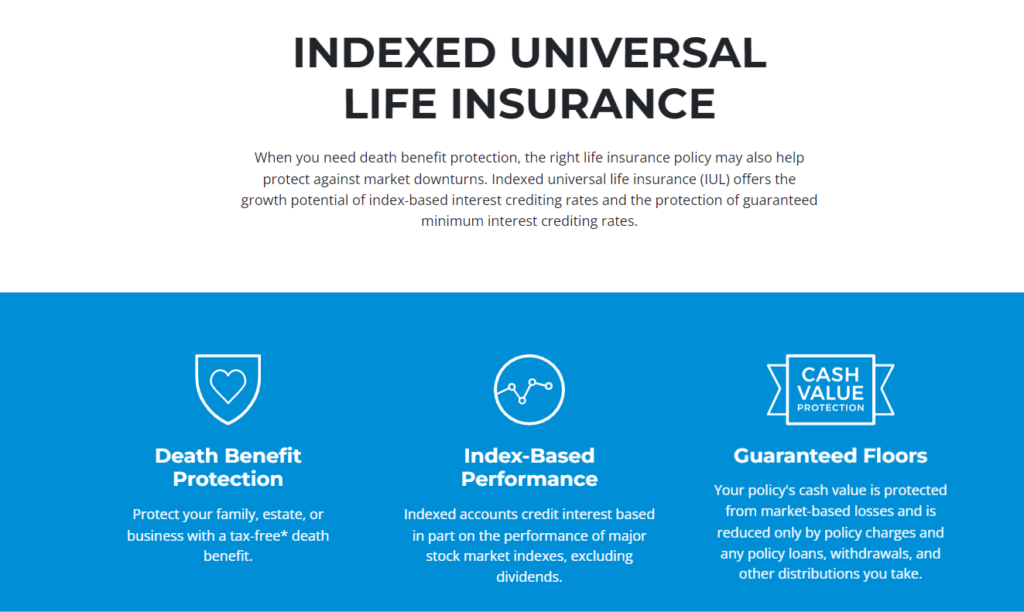
Numerous of Penn Mutual's indexed accounts featured an ensured 1% floor, which means that even in down market years, you make interest to balance out the ongoing cost of the survivor benefit. Regardless of this 1% floor, Penn Mutual still offers competitive caps on its S&P 500 techniques. Unlike the other finest IUL companies on this list, Penn Mutual does NOT offer Volatility Control Index techniques.
Expert Insurance Advice for Choosing Coverage
(In case you missed it above, VCIs are algorithmic market timing techniques handled by well-known financial investment banks with high internal costs and a lack of openness). Competitive Caps on the S&P 500 (often with a 1% flooring instead of 0%)The capability to raise your S&P 500 cap (for an additional cost or spread of around 3%)Uncapped S&P 500 crediting strategies for optimum growthWith Penn Mutual's contractually locked 6% policy loan rate for the life of its IUL policy, you can keep your cash value operating in the S&P 500 Index even while borrowing versus it for emergency situations or outside investment opportunities.
Allianz happens to be the just on the list and a foreign stock business at that. It's valid to stress that a German moms and dad business might not have loyalty to American insurance policy holders if financial times get difficult, but others like the reality a foreign stock company has varied sources of profits in diverse insurance markets.
Insurance in Cypress CAThis enables them to use their "rate lock function," where IUL policy owners can freeze whatever gains they have at any point throughout the year. Nevertheless, it's worth noting that you can only do this with their different volatility control indexes (VCIs) and not the pure S&P methods. In reality, Allianz also has different charge options that enable you to increase your direct exposure to their indexed choices.
Allianz is among the finest IUL companies because of their diverse set of IUL investment optionsIt's worth noting that I've been an Allianz insurance policy holder since 2014, and I can vouch for the truth that my IUL caps and involvement rates aren't as competitive as what they've regularly offered on whatever their latest item is.
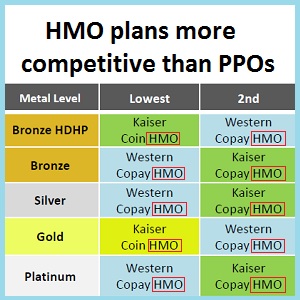
PPO vs HMO Health Insurance Explained
It's important to stress-test how Allianz's IUL policy holds up at lower crediting rates compared to the other top Indexed Universal Life companies. A large variety of exotic indexes to pick fromRate-lock function when using the volatility control indexesAbility to be more aggressive with a 40% multiplier (for a 1% charge)Locked 5% loan rate to borrow versus any of the indexed accountsTheir "Index Lock" just deals with Volatility Control Indexes, not the pure S&P methods.
That really is why Nationwide is one of the leading IUL business. Not only that, but they are a real shared company, indicating they have no outdoors stockholders nor a holding company to siphon profits to.

Latest Posts
Optimizing Indexed Universal Life Growth Benefits for Retirement
Best IUL Strategies for Wealth Growth
Cheap Family Health Insurance Rates in the US